
CBDT Removes Arrest and Detention from Tax Recovery Rules: What Does It Mean for Taxpayers?
Tax recovery rules have changed but this does not mean unpaid tax can simply be ignored.
On 17 September 2026, the Central Board of Direct Taxes (CBDT) notified the Income-tax (Fourth Amendment) Rules, 2026, bringing several changes to the Income-tax Rules, 2026.
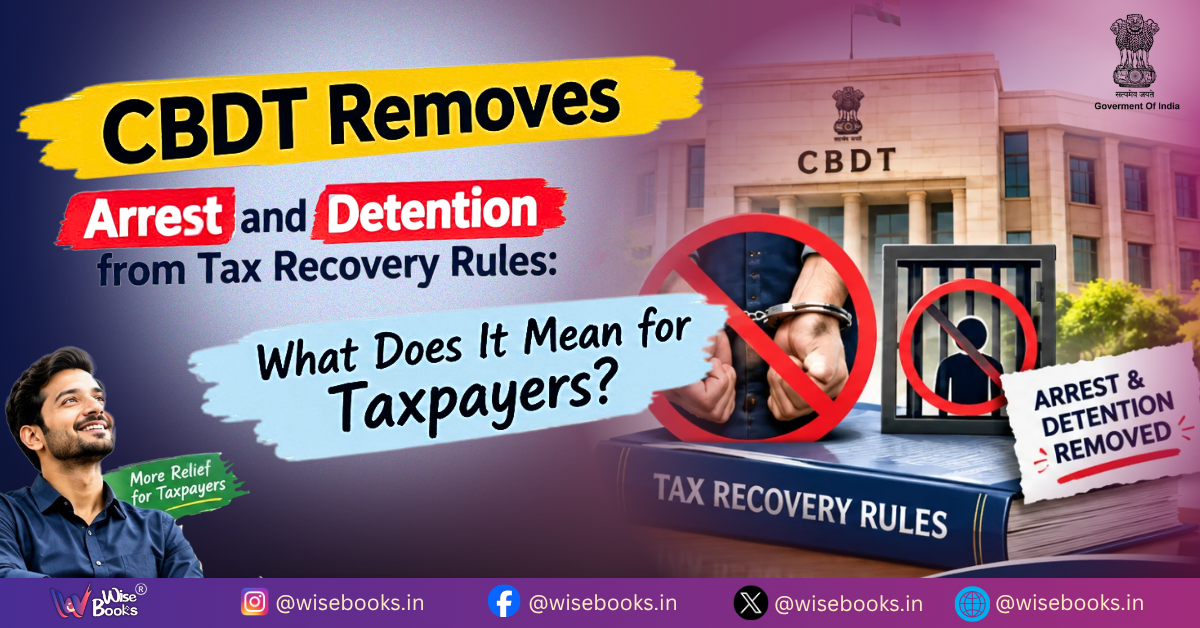
One of the most notable changes is the removal of provisions relating to arrest and detention of a tax defaulter from the prescribed tax-recovery mechanism under Rule 225.
The change has attracted attention because arrest and detention were among the recovery measures provided for under the earlier framework. However, the important point for taxpayers is simple: the removal of these provisions does not remove the tax liability or stop the recovery of outstanding dues.
What Has CBDT Changed?
Rule 225 of the Income-tax Rules, 2026 sets out the procedures for recovering tax arrears.
Through the September 17 notification, CBDT has omitted the provision that referred to arrest and detention in prison as a mode of recovery. It has also removed several sub-rules that dealt with the procedure surrounding arrest, detention, custody, release and related matters.
The relevant amendments have been given retrospective effect from 1 April 2026, the date on which the Income-tax Act, 2025 and the Income-tax Rules, 2026 came into force.
In simple terms, arrest and detention are no longer part of the prescribed recovery process under amended Rule 225.
But there is an important distinction.
Does This Mean Tax Defaulters No Longer Have to Pay?
No. The amendment changes the method of recovery, not the underlying tax liability.
If a taxpayer has an outstanding tax demand, the Income Tax Department can still use other recovery mechanisms available under the law.
These include measures such as attachment and sale of movable or immovable property and other prescribed recovery mechanisms.
So, the message is not:
“Tax dues don't have to be paid anymore.”
It is:
“The prescribed recovery mechanism no longer includes arrest and detention under Rule 225.”
That distinction is important because headlines such as “tax defaulters cannot be arrested” can otherwise give taxpayers the wrong impression.
Why Is This Change Important?
The change reflects a broader shift in India's tax administration under the new income-tax framework.
The Income-tax Act, 2025 and the accompanying rules came into effect from 1 April 2026. The government's broader tax-policy direction has also included reducing criminal consequences for certain technical or procedural defaults.
In this context, removing arrest and detention from the prescribed tax-recovery mechanism represents a move away from personal detention as a recovery measure, while keeping other mechanisms available to recover outstanding amounts.
The explanatory rationale behind the change is that other modes of recovery are considered sufficient.
How Can Tax Dues Still Be Recovered?
The Income Tax Department still has several tools available when tax arrears remain unpaid.
Depending on the circumstances and applicable provisions, recovery can involve attachment and sale of property or other legally prescribed mechanisms.
This means that removing arrest does not make tax recovery less important for taxpayers.
In fact, it makes timely compliance and responding to tax demands just as important.
A taxpayer receiving a demand should first understand why the demand has arisen.
It could relate to an actual tax liability, but it could also involve issues such as a mismatch in tax credits, incorrect reporting, or other information that needs to be examined.
That is why taxpayers should not simply ignore an outstanding demand because the recovery rules have changed.
A Change in Recovery — Not a Cancellation of Liability
This is perhaps the most important takeaway from the amendment.
Think of it this way:
Earlier:
Tax arrears → multiple recovery mechanisms, including arrest and detention under the prescribed Rule 225 process.
After the amendment:
Tax arrears → recovery continues through the other mechanisms available under the law, while arrest and detention have been removed from Rule 225's prescribed recovery process.
So the taxpayer's obligation to pay legitimate outstanding tax dues remains.
The change is about how the government can enforce recovery, not whether the taxpayer owes the money.
What Else Changed in the September 17 Notification?
The CBDT notification was not limited to tax recovery.
It also made changes relating to electronic communication in faceless proceedings and extended certain registration timelines under the new income-tax framework.
For existing valuers and authorised income-tax practitioners, the relevant registration deadline has been extended from 30 September 2026 to 31 March 2027. The notification also substitutes the prescribed registration forms for valuers and authorised income-tax practitioners.
This makes the September 17 notification broader than just the arrest-related change.
What Should Businesses and Taxpayers Take From This?
For taxpayers and businesses, the practical lesson is not to focus only on the headline.
“Arrest and detention removed” does not mean “tax recovery removed.”
Outstanding tax demands can still have financial consequences, and other recovery mechanisms remain available.
Businesses should therefore continue to:
- Reconcile tax demands with their records.
- Check AIS, TDS and other tax information where relevant.
- Respond to genuine outstanding demands within the applicable process.
- Keep books and supporting documents properly maintained.
- Seek professional advice where a demand is disputed or unclear.
The change is significant from a tax-administration perspective, but it should be understood correctly.
The Bigger Picture
India's income-tax framework is undergoing a broader transition with the implementation of the Income-tax Act, 2025 from April 2026.
The latest amendment shows one aspect of that transition: while the government continues to retain mechanisms for recovering unpaid taxes, the prescribed recovery framework under Rule 225 no longer includes arrest and detention.
For taxpayers, the takeaway is straightforward:
The recovery method has changed. The tax obligation has not.
As India's new income-tax framework continues to evolve, businesses and taxpayers will need to pay attention not only to tax rates and filing deadlines, but also to changes in compliance, reporting and recovery procedures.


Comments
No comments yet. Be the first to comment!